Businesses that publicly demonstrate good sustainability performance can reap financial, reputational and other benefits, but it’s important to minimise the cost of any reporting on sustainability issues and to focus efforts on improving aspects of sustainability where the benefits outweigh the costs.
Features
Turning sustainability compliance into business opportunity
By
on 12 March 2026
Most of the companies I speak with say that sustainability reporting compliance is just a cost. For some, that burden is already here with mandatory SECR (Streamlined Energy and Carbon Reporting) and TCFD (Taskforce for Climate-related Financial Disclosures) disclosures. Others are expected to report because they operate in other countries, like the European Union with their CSRD (Corporate Sustainability Reporting Directive), or to meet their clients’ demands. Many more are anticipating the launch of the UK’s new SRS (Sustainability Reporting Standards).
And it’s not surprising that this evolving amalgamation of acronyms is so often viewed as a drain on British businesses. It can take many months to just be able to comply with one of these frameworks.
Even in medium-sized businesses, preparing these reports can easily become someone’s full-time role, while larger businesses often need a dedicated disclosure team. One estimate found that larger European companies will spend up to one per cent of their annual revenues complying with CSRD in its first year. It’s no surprise that businesses view this expenditure as a cost, with fragmented data, exhausted teams, and limited positive impact.
 Many companies end up with a list of over a dozen material issues that they’re working towards, but the high-performing ones rarely have more than a handful. Photograph: iStock
But there is another way. Many companies have found a way to ‘thread the needle’ – striking a balance between sustainability and value creation. Surveys and research consistently show that sustainability can improve revenue growth and overall profitability, including through greater customer satisfaction and talent attraction.
ESG-ranked stocks benefit from more resilient growth, and outperformed the US stock market in the early days of the pandemic. Unilever was one such company that proved this possible. Under the leadership of Paul Polman, their portfolio of sustainable brands consistently outperformed their broader portfolio, while creating impact on issues ranging from body image to climate justice. So, what can we learn from these companies? How have they turned sustainability compliance into business opportunity?
Key steps
There are two steps that we’d recommend, especially for companies just starting out with corporate sustainability. One is how a company approaches their reporting and disclosures; the other is creating precise action where the benefits significantly outweigh any costs.
First, companies should look to minimise the costs of their compliance. All too often, companies create vast disclosure reports that pull from data across the business and beyond to present a dizzying and unnecessarily complex picture, built upon unwieldy manual processes.
Instead, companies can reduce the burden by presenting only essential, decision-useful information. Many of these standards are designed to give investors the information they need, so work with your investors and CFO to understand what it is that they really want to see and what they don’t. For example, some standards ask for a list of material issues, and while an internal and external double materiality assessment is best practice, it may also be too much for a company at an early stage.
Equally for those reporting against multiple standards, identifying the highest common denominator on a particular area can stop a business reporting several similar but slightly different data points.
Additionally, companies can minimise their ongoing costs by investing surgically and early.
The initial costs of compliance in the first year can be significant, but the aim should be repeatable, auditable and consistent processes that are cheaper and easier to implement in subsequent years. For example, the right technology platforms can accelerate carbon accounting, and come with inbuilt checks and balances to ensure repeatable and accurate results.
Equally, learn from the experience of others, be that through networks, trade associations or specialist consulting teams, especially those who can support a project while training senior leaders and project teams to implement by themselves in future years. By reducing the scope and cost of these disclosures, and minimising the pain of future years, companies can create significant savings, but that's still only half the story.
 Alastair Loasby: Companies can minimise their ongoing costs by investing surgically and early.
Learn lessons
The second stage is to learn from those disclosures and align sustainability action with your growth strategy.
Crucially, this will differ by sector, size and ambition, with large businesses likely acting on more issues, but medium businesses can do this by starting with a ‘T’ strategy, combining essential activity across a breadth of issues with deep impact on a single, material issue.
This starts by reducing a company’s risk by acting on essential areas. Depending on sector and size, key stakeholders, from customers to employees, will likely expect action on some sustainability topics. I’ve met B2B firms who have lost work because they haven’t had a robust net zero target. Some have lost high performing talent because they haven’t created an inclusive culture, and a few have only been able to access funding if they reach a certain level of ESG maturity.
The key here is to speak with your most important stakeholders and benchmark your performance against competitors to understand what is really expected from your business. This approach helps to reduce any risk from sustainability issues, laying the groundwork for resilient growth.
In addition to that risk mitigation, successful companies then create business value through impact on a single, material issue, aligned to their strategy. This will vary from business to business but there are some common themes. A firm where high-performing talent is a key enabler might aim to be the most inclusive business in their sector or prioritise community engagement to significantly boost colleague engagement and productivity. A business that relies on raw materials threatened by climate change might focus on supply chain resilience, climate adaptation and nature-based resilience.
A B2B firm that relies on reputation and client relationships might seek to create an outsized impact in their local community, creating opportunities to engage and even co-deliver projects with clients. A premium consumer goods company might recognise that sustainable products enjoy more loyal customers, so will focus on tangible impact that resonates with their target audience. The list goes on, but the approach is the same: investing to create a meaningful, demonstrable impact on an issue that your stakeholders hold dear and that unlocks your business’s growth potential.
Positive impact
This is an opportunity to not just grow your business, but to make a difference. A chance to tackle the breakdown of nature, stem inequality in our society or even to save lives. Positive impact must be at the heart of this strategy for it to succeed, and only by being targeted and committed can a company new to sustainability maximise their value.
One CEO of a bank recently described how their organisation had ‘threaded the needle’ of sustainability in practice. They started off trying to do everything, but had grown much more targeted and forensic in their actions, only acting on a few areas that were meaningful for their clients and people, that were linked to their strategy, and that were ultimately impactful.
Many companies end up with a list of over a dozen material issues that they’re working towards, but the high-performing ones rarely have more than a handful. That focus can reduce the burden of compliance, meet the basic expectations of your clients, and create impact while catalysing your business plan. And that approach is a model for us all.
For more information go to:
saffery.com
Contact Alastair Loasby at:
saffery.com/our-people/alastair-loasby
[email protected]
Alastair Loasby is Director of Sustainability and ESG Saffery LLP
FEATURES
Who is the wolf in your life? Listening to the people behind the hard hat
By Inna Cebotari, Kinth Square on 02 October 2026
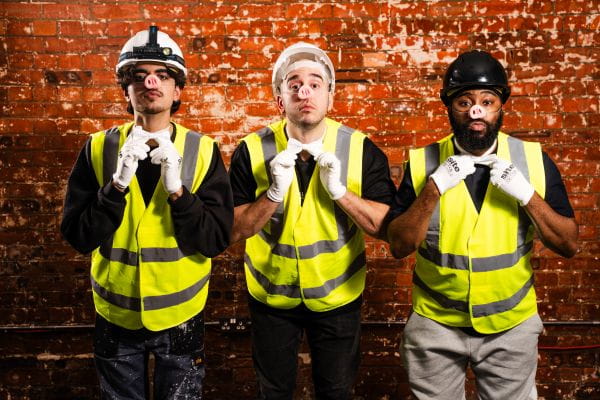
A new play explores the lives of migrant construction workers in the UK, using humour, real-life experiences and physical theatre to capture the banter, friendships and absurd moments that make life on site bearable, alongside the pressures that often go unseen. Ahead of the play’s premiere in London on 12-14 November, playwright Inna Cebotari explains how Three Little Pigs aims to add to the public debate about how best to support the wellbeing of construction workers.
Eliminating barriers in reporting: how conversational AI can unlock safety engagement
By Julian Taylor, ecoPortal on 04 October 2026
Online reporting systems that require lengthy and cumbersome form filling and typing can discourage workers from reporting safety incidents and concerns. However, AI-powered mobile apps that allow reporting simply by speaking can simplify and speed up the process, boosting reporting rates and overall staff engagement with safety systems and culture.
Why UK employers need to rethink recruitment, retention and support for older workers
By Orchie Bandyopadhyay on 04 October 2026
With workers over the age of 50 now comprising almost one third of the entire UK workforce, recruiting and retaining older workers is now core to the success of the economy. However, not all employers are offering what’s needed to retain and recruit older workers, and ageist attitudes, limited flexible working opportunities, and employment support that doesn’t fit with health, caring, or other responsibilities are leaving too many people locked out of the labour market.